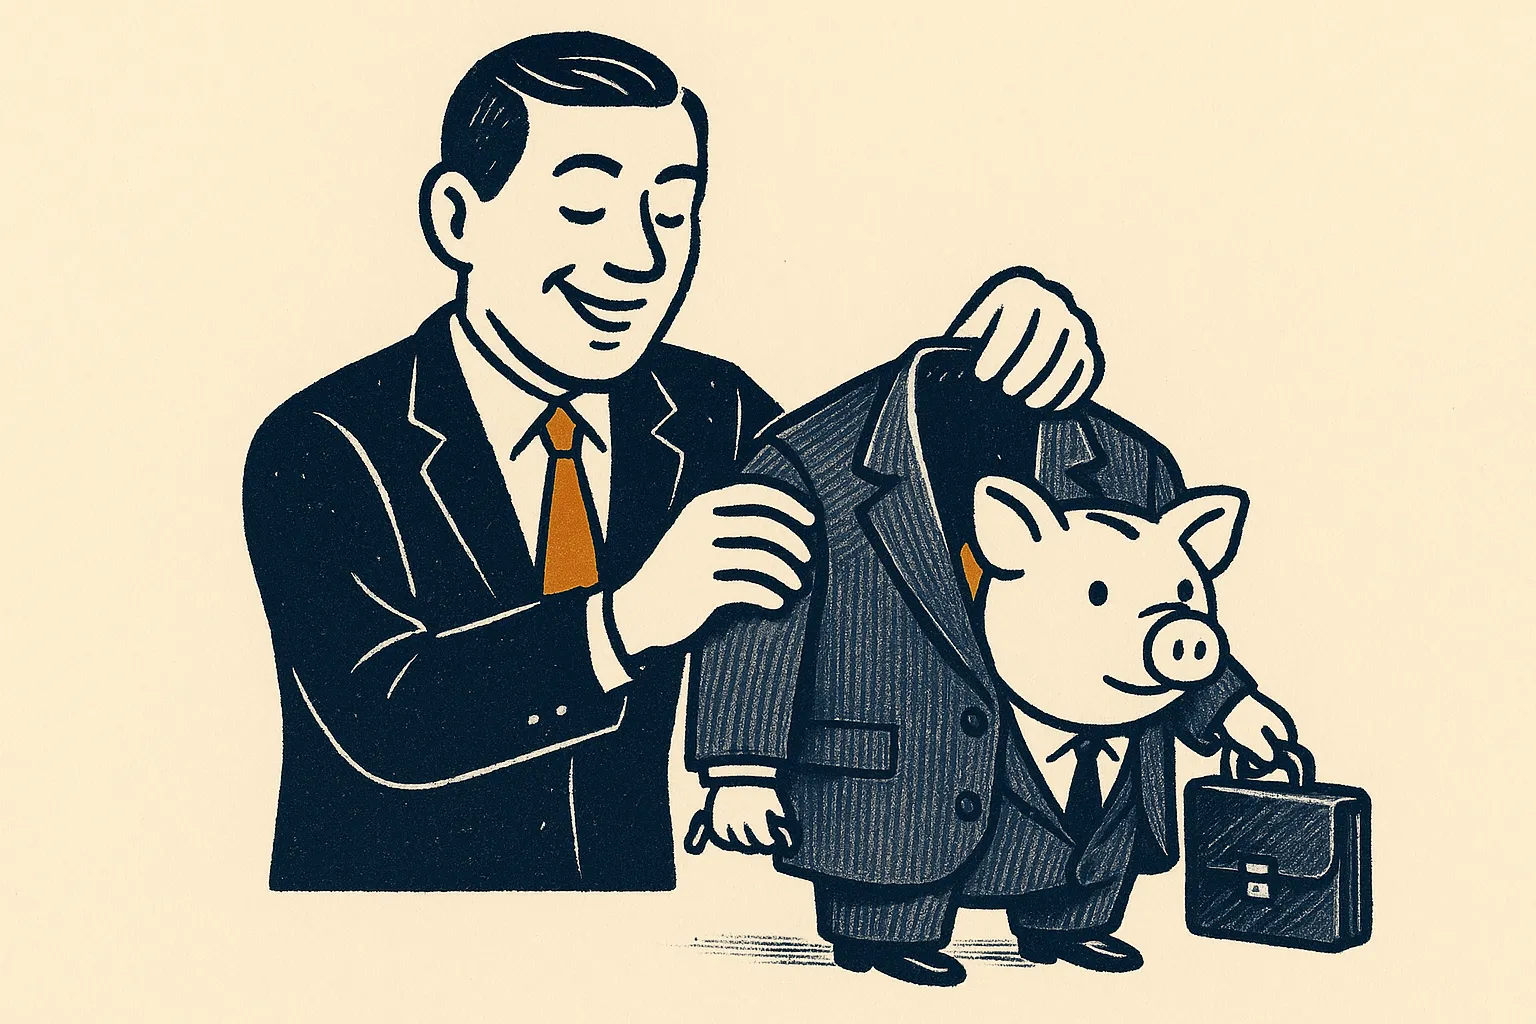
Let’s start with the part that makes this file hard to write. When someone offers to insure your child, they are not really selling a financial product. They are asking a question no parent wants to sit with, then offering to make the discomfort go away for a few dollars a month. It’s a powerful sales position, and the people who use it know how powerful it is.
So we’ll be careful and plain. Nothing below makes light of the fear underneath this decision. The goal is only to separate what a child policy actually does from what the pitch implies it does — because those two things are often far apart, and the gap is where your money goes.
The pitch, and the premise it quietly skips
The core purpose of life insurance is income replacement. You insure a life because other people depend on the money that life brings in — a mortgage, groceries, a college fund, all resting on someone’s paycheck. When that person dies, the insurance stands in for the paycheck that stopped.
A child, by that logic, is the one person in your household who almost never needs it. A child earns no income. No one’s rent depends on a seven-year-old. So the standard justification for buying coverage — replace the money this person would have earned — simply doesn’t apply. This is the premise the pitch skips, because saying it out loud would end the conversation.
What the pitch offers instead is a swap. It trades the real reason people buy life insurance (protecting dependents) for softer, emotional ones: locking in a healthy child’s insurability, “getting a head start,” building a nest egg, or just the feeling that you’ve done something protective. Some have a kernel of merit, which we’ll get to honestly. But notice the move: you came in thinking about protection, and you’re being sold a savings-and-sentiment product wearing protection’s clothes.
Life insurance answers the question "who loses money when this person dies?" For a child, the honest answer is usually: no one, in the income sense. The pitch works by replacing that question with a different one — "don't you want to protect your child?" — where the answer is always yes. Watch for the switch.
What a child rider actually is
Strip away the emotion and two very different things are sold under the same warm banner. The first is a child rider, and it is the modest, defensible one.
A child rider is a small add-on to a parent’s policy. For one low, flat cost, it typically covers all your children — including ones born later — with a small amount of term coverage, often in the range of $10,000 to $25,000 per child. It is not a policy on the child; it’s a feature bolted onto yours.
There are two genuinely reasonable cases for it, worth naming honestly:
- Final-expense peace of mind. The subject is grim, so we’ll be brief. If the unthinkable happens, a grieving family should not also be handed a bill. A modest final-expense cushion means funeral and related costs, and time away from work, are not a financial emergency layered on top of a personal one. That is a real, if narrow, function.
- A hedge on future insurability. Many child riders let the coverage be converted into a permanent policy when the child grows up, usually without a new medical exam. For the small number of children who develop a serious health condition young, that conversion feature can matter. For most, it won’t — more on that below.
A child rider is cheap precisely because a child’s death is, statistically, rare, and the coverage amount is small. That’s the tell that it’s priced honestly: it costs little because it does little. Reasonable is not the same as necessary, but a few dollars a month for a real, if unlikely, contingency is not where families get hurt.
The “start their policy early” pitch is a different animal
Where families do get hurt is the second product: a standalone whole life policy taken out on the child, sold with lines like “lock in their low rate now,” “start their policy early,” or “build cash value for college.” This is not a small rider. It’s a full permanent policy, with a permanent premium, and it deserves real skepticism.
Take the three claims in turn.
“Lock in low rates while they’re young and healthy.” Premiums do rise with age. But the premium is low because the risk is low — you’re not beating the system, you’re pre-paying decades of coverage on a person who doesn’t need coverage yet. And “healthy now” cuts the other way: the vast majority of children stay insurable into adulthood on their own. You’re insuring against a problem that, for almost every child, never arrives.
“Build cash value for college.” This is the claim that costs the most. A whole life policy does build cash value — slowly, and after heavy early costs. First-year premiums on permanent policies are largely eaten by commissions and expenses, so the accessible cash value trails what you’ve paid in for years. Here’s the shape of it, illustratively:
| Contributed over 18 years | Child whole life — cash value | Same dollars, boring college account |
|---|---|---|
| ~$25 / month ($5,400 total) | ~$4,800 | ~$8,000–$9,000 |
The problem isn’t that the cash value is fake. It’s that if the goal is college, a life insurance policy is a slow, expensive wrapper around a savings account — one that also happens to pay a commission to the person recommending it. Ordinary education-savings accounts do the college job more directly and usually with more to show for it. (For why the incentive to sell the pricier product runs so deep, see our file on how agents actually get paid.)
The one real kernel: guaranteed insurability
Honesty cuts both ways, so here is the strongest argument for insuring a child — the one worth taking seriously.
If a child develops a serious medical condition early in life, that condition can make them hard or impossible to insure as an adult at normal rates. A policy or rider bought before any diagnosis locks in coverage they might not otherwise be able to get. This is the guaranteed insurability argument, and unlike the college pitch, it points at a real risk.
But be clear-eyed about the scope. This matters for the rare child who develops a significant condition young — not the typical one. For the overwhelming majority, insurability is never in question; they grow up, apply as adults, and qualify on their own. Buying an expensive permanent policy for every child to hedge an outcome that affects very few is paying full price for a lottery ticket most families never cash.
If the insurability hedge genuinely appeals to you, buy the cheapest form that delivers it — the small child rider with a conversion feature, or a modest guaranteed-issue option — not a large whole-life policy sold on the same worry. You can buy the peace of mind without the commission attached to it.
Guaranteed insurability is the genuine kernel, which is exactly why good salespeople lead with it and then upsell far past it. The risk is real; the response being sold is usually oversized. "Protect their insurability" justifies a small rider. It does not, by itself, justify a five-figure permanent policy.
What to actually do
If you take one thing from this file, let it be the order of operations. The strongest protection for a child is not a policy with their name on it — it’s making sure the adults they depend on are fully covered.
- Insure the income first.Before a dollar goes toward a policy on your child, make sure every income-earning parent is adequately covered. A working parent dying underinsured is the financial catastrophe a child actually faces — this is where your premium dollars protect them most.
- If you want coverage on the kids, use the rider.A modest child [rider](/glossary/rider/) on a parent's policy covers all your children for one low cost, handles the final-expense contingency, and often includes a conversion option. It's the honest version of insuring a child.
- Decline the standalone whole-life "gift" policy.Unless you have a specific, unusual reason, a permanent policy on a healthy child is an expensive way to make a small point. The cash value grows slowly and the commission is real.
- Separate the college goal from the insurance goal.If you're saving for education, use an account built for education. Don't let "cash value for college" route your savings through an insurance product that keeps a cut.
- Check the [beneficiary](/glossary/beneficiary/) and conversion details.On any rider or policy, confirm who receives the benefit and whether coverage can convert later without a new medical exam. Those two features are where the modest, sensible value lives.
A child is not an income earner, so the usual reason to buy life insurance doesn't apply to them. A small child rider — for final-expense peace of mind and a hedge on future insurability — can be a reasonable few dollars a month. A standalone whole-life policy sold as a head start or a college fund is usually an expensive way to make a small point.
Fund the parents' coverage first. That is the decision that actually protects your child. Everything else is optional — and should be priced, and questioned, like anything else you buy.
This file is general information from an independent watchdog, not financial, tax, or legal advice. Your family’s situation is your own; talk it through with someone who has no commission riding on the answer.
File 063 · Investigation · Tip line: [email protected]