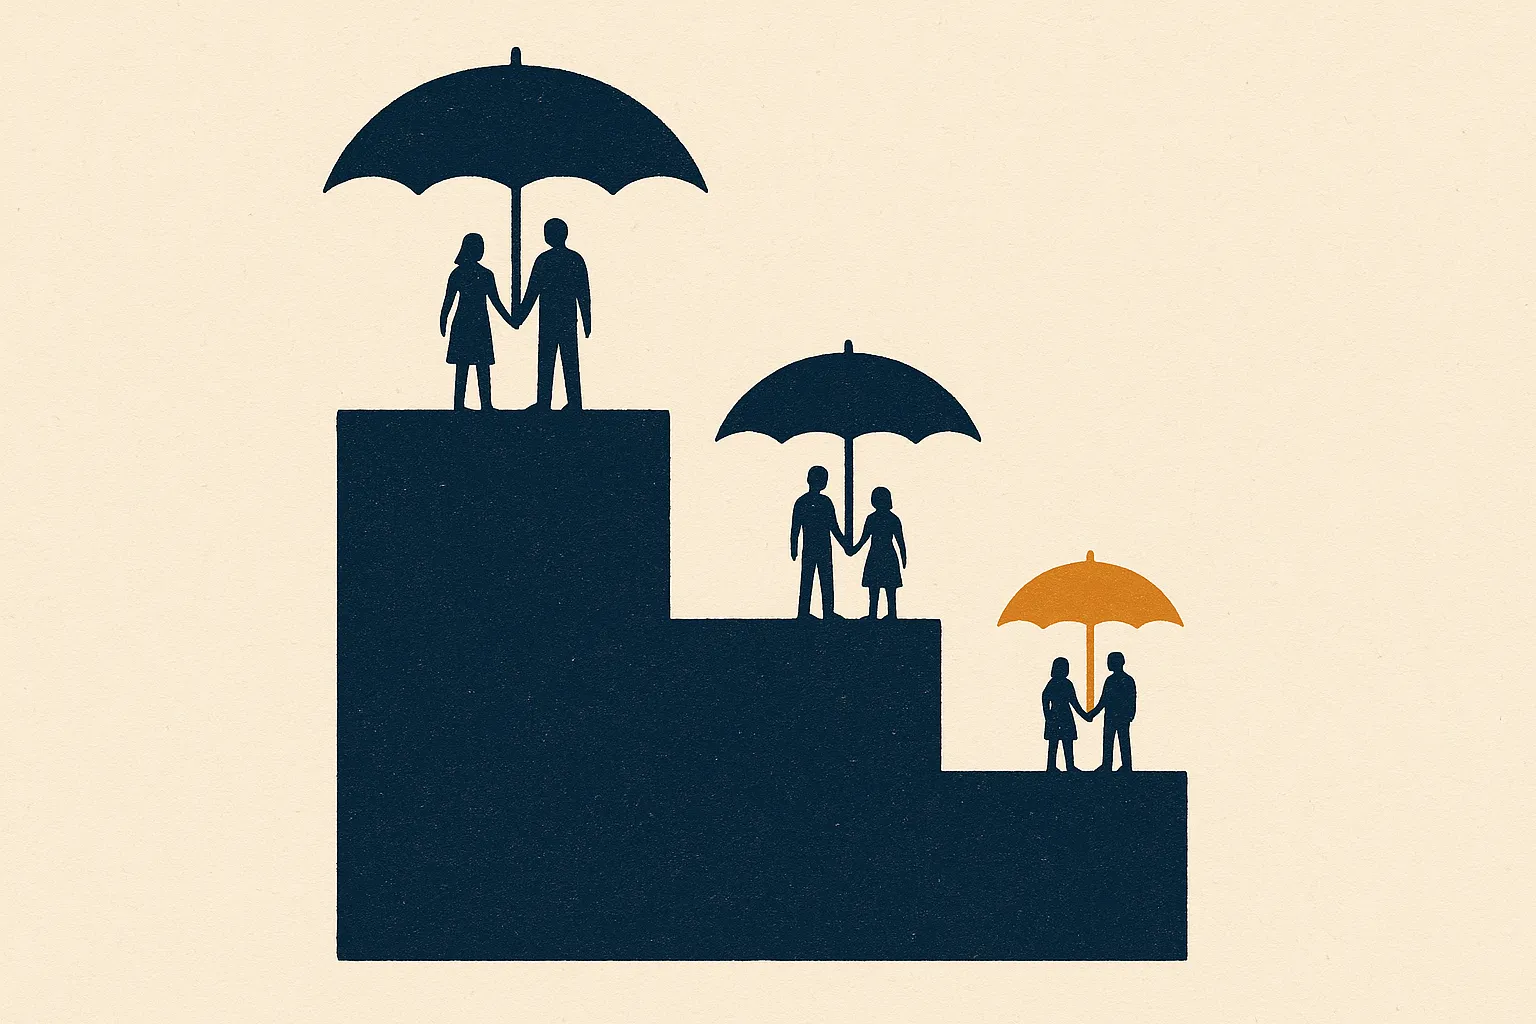
Most life insurance buyers have a need that shrinks over time. The mortgage gets paid down. The kids launch. The retirement account accumulates. The working spouse approaches their own retirement. By year 25 of a typical 30-year level term policy, the original need that justified the death benefit has often shrunk by half or more.
A term ladder takes advantage of this. Instead of one $1,000,000 30-year policy, you buy:
- $500,000 of 30-year term (covers the long retirement-runway need)
- $300,000 of 20-year term (covers the kids-to-launch need)
- $200,000 of 10-year term (covers the early mortgage-payoff need)
Same $1,000,000 of coverage in years 1–10. Drops to $800,000 in years 11–20. Drops to $500,000 in years 21–30. Matching, roughly, your actual declining need.
The Math
For a 40-year-old male nonsmoker in good health, the laddered approach typically prices about 20–28% lower than a single 30-year $1M policy. Here’s the arithmetic, so you don’t have to take our word for it.
Representative preferred-rate premiums — directionally accurate, but get your own quotes to confirm:
| Coverage | Monthly | Runs through |
|---|---|---|
| Single: $1,000,000 · 30-yr | ~$85 | Year 30 |
| Ladder: $500k · 30-yr | ~$48 | Year 30 |
| Ladder: $300k · 20-yr | ~$22 | Year 20 |
| Ladder: $200k · 10-yr | ~$11 | Year 10 |
- Single policy: ~$85/mo × 360 months ≈ $30,600.
- Ladder:
$81/mo for years 1–10, then the 10-year layer drops off ($70/mo for years 11–20), then the 20-year layer drops off (~$48/mo for years 21–30). That’s ($81 × 120) + ($70 × 120) + ($48 × 120) ≈ $23,880.
In this example the ladder saves about $6,700 for the same coverage in the years you actually need it — roughly 22% — and the gap widens to five figures at higher face amounts and older starting ages, where the single-policy premium climbs fastest. The five minutes is real: pull three quotes and one, and compare the totals.
The trade-off is real and worth naming: if your circumstances don’t change as expected, you have less coverage in later years than the single-policy approach would have given you. For most buyers this is the right trade. For some buyers — those expecting permanent dependents, late-life children, or estate-tax exposure — it isn’t.
An independent agent can run the math both ways and tell you which fits your actual situation. A captive agent earning commission off the larger single policy will, predictably, not raise the laddered alternative on their own.
File 041 · Investigation · Tip line: [email protected]